
What if the fastest-looking route to an instant cash loan today is the one that needs the closest review? When money feels urgent, a text offering quick funding can seem like a direct path to relief. But a message may only advertise a loan or link to an online application. It doesn’t complete the loan or guarantee approval or funding.
It’s reasonable to want clear answers before sharing personal information or agreeing to repay a loan. A text can be genuine, misleading, or a scam, so check who sent it and where its link leads. Then compare the offer with a secure online application, where you can review the process before deciding what to do next.
This article explains what “text message loan” offers usually mean, how they differ from applying through QuickCashDirect, and what to examine before accepting a lender’s offer. QuickCashDirect is an online referral service that connects applicants with a network of lenders. Submitting an application isn’t the same as accepting a loan. Review the lender’s identity, disclosures, repayment schedule, total cost, funding timing, and information requests before authorizing anything.
Key Takeaways
- A “text message loan” may be a promotion or application link, not an approved loan.
- Compare who initiated contact, where the link leads, and whether the lender and next steps are clearly identified.
- Watch for pressure tactics, guaranteed-approval claims, unclear costs, and unusual upfront payment requests before sharing information.
- Before pursuing an instant cash loan today, review the APR, fees, repayment dates, total amount due, and potential impact on essential expenses.
- QuickCashDirect’s referral process can connect applicants with potential lender options, but it does not guarantee a match, approval, terms, or funding time.
What Are Text Message Loans, and Can They Provide an Instant Cash Loan Today?
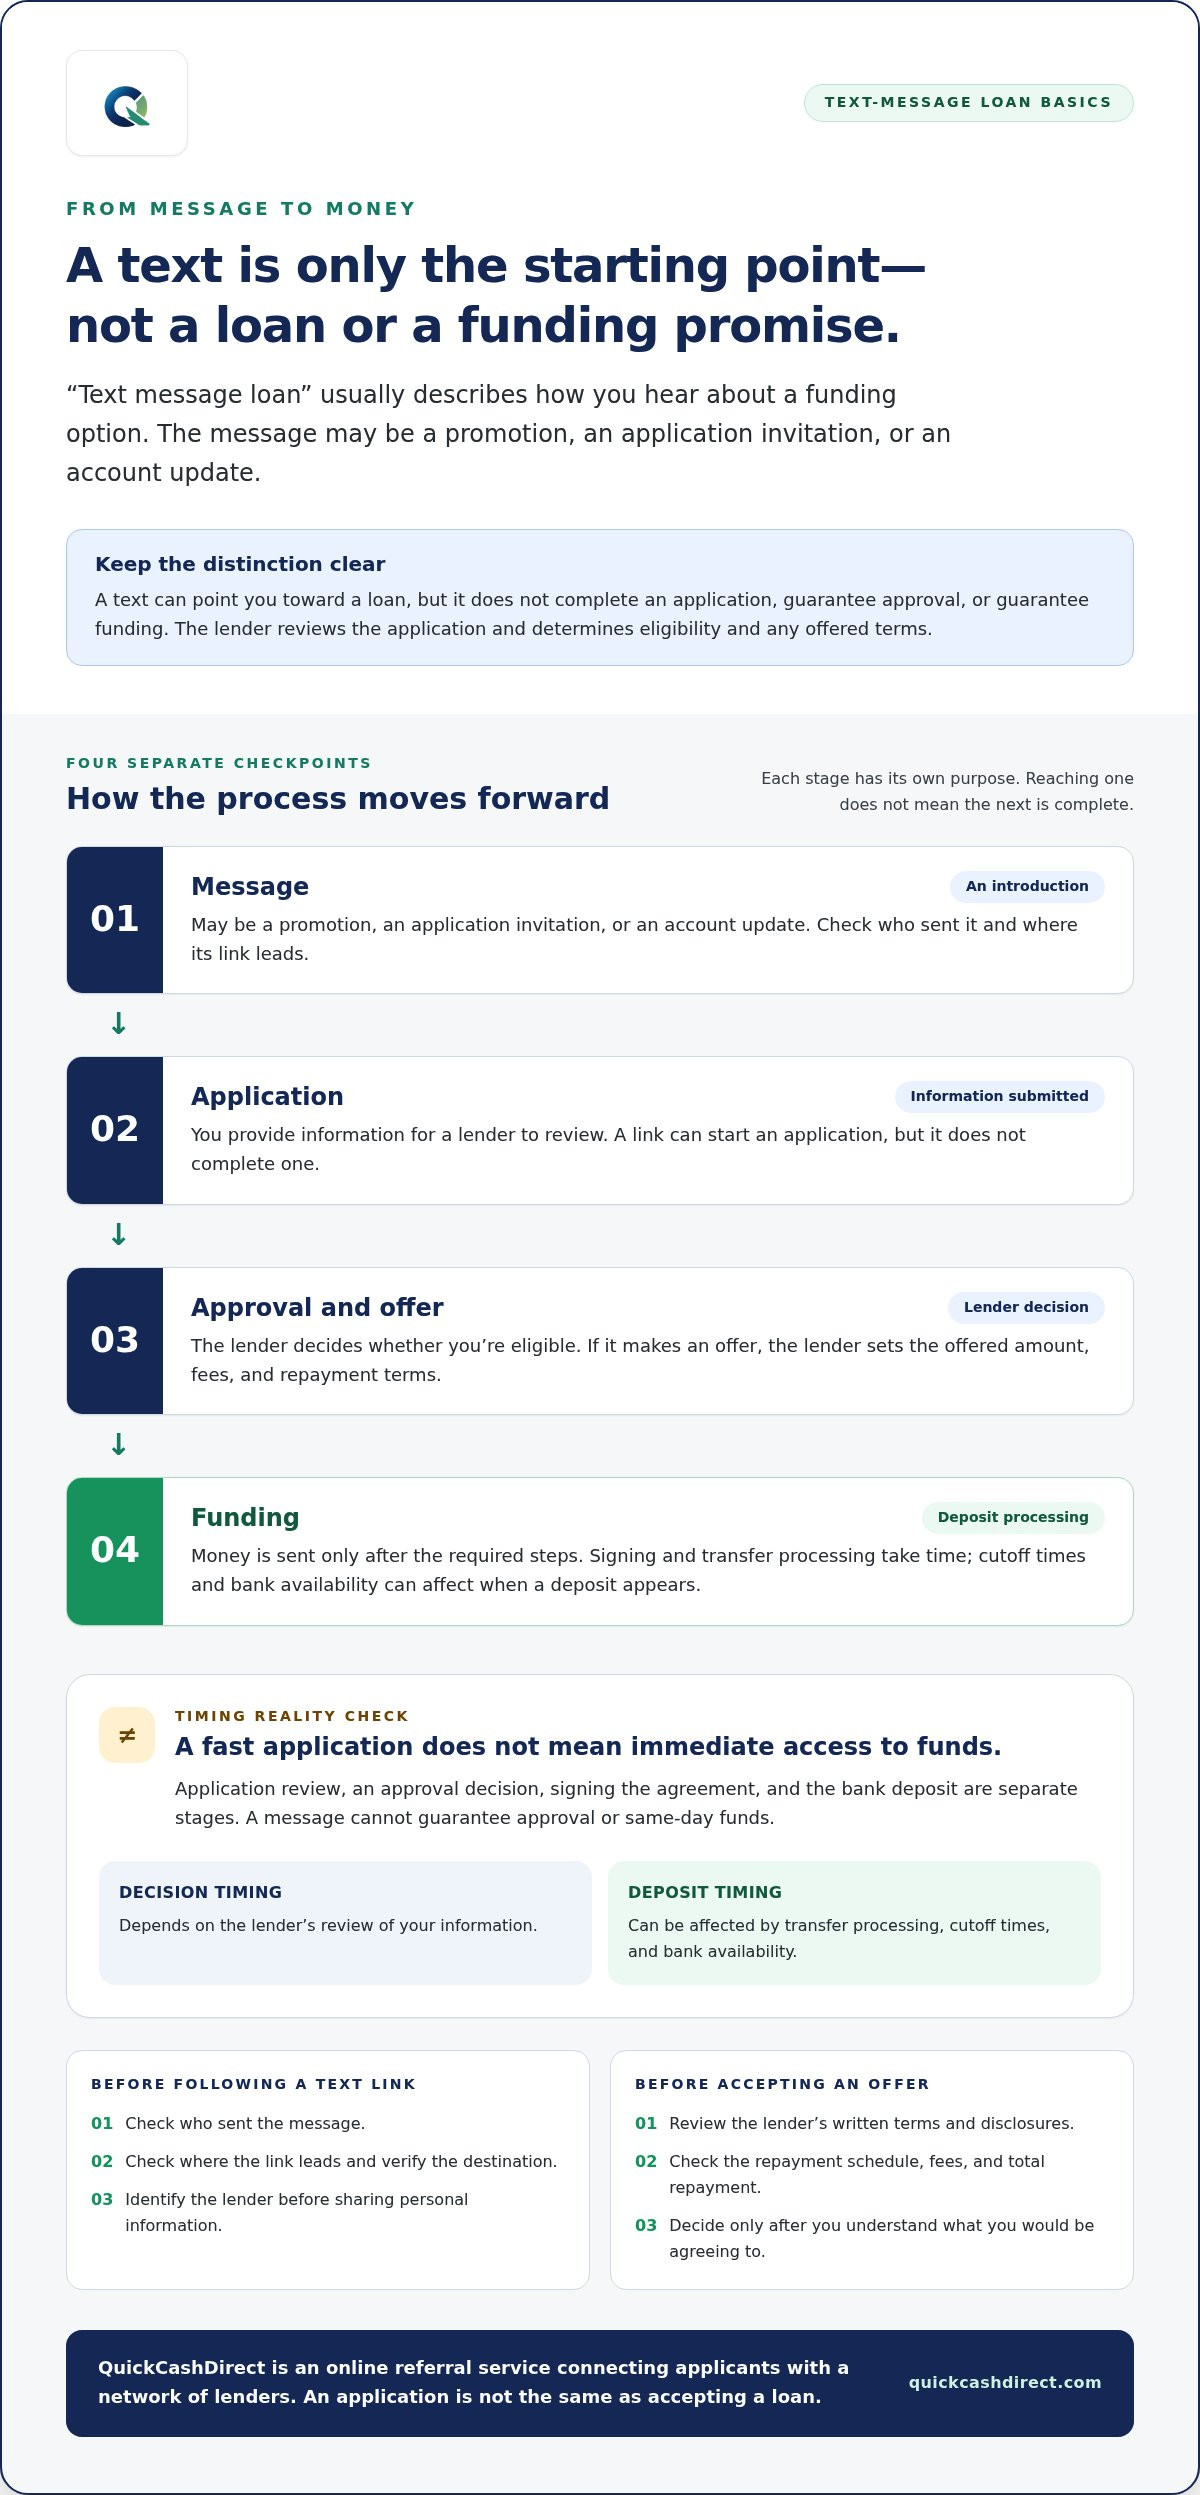
A text message can point you toward a loan, but it isn’t itself a loan. “Text message loan” usually describes how someone hears about a funding option: through a promotion, an application invitation, or an update about an application. It doesn’t name a distinct loan category with standard terms. Payday loans are one established short-term loan category; for background, see information about payday loans.
Read the message as a prompt to check the details, not as proof that funds are waiting. The lender evaluates the application and, if it makes an offer, sets the eligibility requirements and loan terms. An instant cash loan today may be possible only after each step is completed. Timing can depend on the lender and the deposit process.
Separate these four steps:
- Message: A promotion, application invitation, or account update.
- Application: Information submitted for a lender to review.
- Approval: A lender’s decision, potentially followed by a loan offer.
- Funding: Money sent after the required steps, with deposit timing affected by processing.
What can a text-message loan offer actually mean?
A marketing message may advertise a potential loan. An application invitation may link to a form where you submit information for review. An account or application update may report a status or request a next step. In every case, check where the link leads and identify the lender before proceeding. A link can start an application, but it doesn’t complete one. The lender, not the message wording, determines eligibility and any offered amount, fees, and repayment terms.
Does a text message mean funds arrive today?
No. Application review, an approval decision, signing the loan agreement, and bank deposit are separate stages. A lender may need to review your information and provide terms before you can decide whether to accept. If you accept, signing and transfer processing still take time. Cutoff times and bank availability can affect when a deposit appears, so a fast application doesn’t necessarily mean immediate access to funds.
A message cannot guarantee approval or same-day funds. Before relying on a promised timeline, distinguish the time it takes to get a decision from the time it takes for money to reach your account. Treat each stage as a separate checkpoint, and review the lender’s written terms before accepting an offer.
Text Message Loan Offers vs. Online Applications: What Should You Compare?
A text can be convenient, but it gives you less context at a glance. Treat it as a route to information, not as a replacement for an application or the lender’s disclosures. Starting an application yourself can make it easier to track where you entered your information and why. Either way, verify the destination and lender before sharing sensitive details.
| What to compare | Text-message offer | Borrower-started online application |
|---|---|---|
| Who initiated contact | A lender or marketer may have sent the message, or it may be unsolicited. | You start the process, so you can more easily connect your visit with your funding request. |
| Destination | A link may lead to a promotion, an application, or another site. Check the full domain before proceeding. | Enter the website address yourself or use a verified bookmark, then confirm the page matches the service you intended to use. |
| Lender identity | The sender’s name may not make clear which lender would review an application. | Look for the identity of the service collecting your information and, if an offer follows, the lender making it. |
| Disclosures and next steps | A short message may not show repayment details or explain what happens after you tap. | The application may explain how information is used for lender matching or review. Read the lender’s offer and disclosures before accepting. |
How do text-based offers differ from applying online?
A text is a notification or a link, not a complete account of the loan. An online application typically collects details for lender matching or review, but the process and any offer depend on the service and lender. Before entering personal or financial information, confirm the destination domain and identify who will receive your application. Don’t assume a familiar-looking message proves the link is genuine.
Which channel gives you clearer terms before acceptance?
The channel alone doesn’t determine how clear an offer is. Check that you can identify the lender and review the repayment schedule, fees, and total repayment before signing or authorizing a transaction. The Consumer Financial Protection Bureau explains how payday loans work and what to consider in its payday loan guidance. For background on the application process, read how payday loans work online.
When considering an instant cash loan today, compare the written terms, not just the speed or wording of an offer. QuickCashDirect’s online funding options provide a starting point for exploring potential options. Review any lender’s offer before deciding.
How to Spot Risky Text Message Loan Offers Before Sharing Information
A message promising an instant cash loan today can create pressure to act quickly. Pause before tapping a link or replying. A warning sign doesn’t prove a message is fraudulent, but unclear details should prompt you to verify the source independently before sharing personal or financial information.
Which warning signs should make you pause?
Be cautious if a message threatens immediate consequences, promises guaranteed approval, or pushes you to act before you can review the terms. An offer should identify the lender and explain the next step. If costs or repayment details remain vague, don’t let the promise of speed rush your decision.
- Check the sender: Does the sender identify a lender you recognize, or is the name vague or unfamiliar?
- Inspect the destination: Does the link appear to lead to the lender’s official site, or does it use an unexpected or misspelled domain?
- Review information requests: Be wary of requests for account passwords, login codes, or other credentials. Don’t send sensitive details in response to a message you can’t verify.
- Question payment demands: Requests for unusual upfront payment methods deserve extra caution. Don’t pay simply to secure a promised loan.
- Look for clear terms: Confirm the lender’s identity, costs, repayment details, and what happens next before considering an offer.
How can you check a message without following its link?
Search for the lender separately or use contact information from a source you reach independently. Compare the name, website, and contact details with what the message claims. Then find the lender’s disclosures and privacy information through that separate route. If you can’t confirm who sent the text or where it leads, don’t use its link or share information through it.
The Federal Trade Commission (FTC) and Consumer Financial Protection Bureau (CFPB) offer consumer-information resources about scams and borrowing. Go to their official websites directly rather than relying on links in an unexpected message. Keep a copy of the text if you need to compare its claims with information you find independently.
Verify the lender through a trusted, separate source before sharing financial information. That pause can help you distinguish a real application path from a message that relies on urgent wording. Even when you’re searching for fast emergency funding, take time to confirm who will receive your information and review the terms before authorizing anything.
How to Compare Loan Terms, Costs, and Repayment Before You Apply
A quick decision can address an urgent cash need, but speed alone doesn’t make a loan affordable. Review the actual offer from the lender before signing or authorizing a transaction. Terms can vary by lender and state, so use the offer disclosures, not a text, advertisement, or referral application, as your source for the loan’s final details.
What loan details should you review before accepting?
Use this sequence to check the full cost and fit of an offer:
- 1. Identify the lender. Confirm the company named in the offer. A referral service can connect applicants with lenders, but the lender makes the offer and sets its terms.
- 2. Confirm the amount. Check how much you would receive and whether it matches the amount you need to cover the expense.
- 3. Review the APR and fees. Read the disclosures for the annual percentage rate and any fees. Don’t judge the cost by the payment amount alone.
- 4. Mark every due date. Note when each payment is due and whether repayment comes as one payment or scheduled installments.
- 5. Calculate total repayment. Find the total amount you’ll repay over the life of the loan, including applicable fees.
- 6. Check missed-payment terms. Read the agreement for the stated consequences of a late or missed payment.
Compare payment dates with your expected income and essential bills, such as housing, utilities, food, and transportation. A payment that looks manageable on paper may leave too little for those expenses when it comes due. Deposit timing can vary, so don’t treat a discussion of possible timing as a promise about when funds will arrive. Consider the expected timing alongside the repayment schedule before relying on a deposit to cover a bill.
What if the repayment schedule does not fit your budget?
Pause if you can’t reasonably make the payments while covering essential expenses. Don’t accept an offer based only on the hope that your budget will work itself out. Late or missed payments may have consequences described in the loan agreement, so understand those terms before committing. When comparing short-term funding, weigh the repayment obligation against other options available to you.
QuickCashDirect is an online referral service, not a direct lender. An application can connect you with potential options, but the lender’s disclosures determine the actual terms. If you’re looking for an instant cash loan today, QuickCashDirect’s online funding options can help you explore potential options. Weigh any offer against your budget before accepting.
How QuickCashDirect Connects Applicants With Potential Loan Options
QuickCashDirect is an online loan referral service, not a direct lender. It connects applicants with a network of lenders that may offer short-term options, including payday loans, cash advances, or installment loans. The service provides a starting point for exploring potential options. The lender, not QuickCashDirect, decides whether to make an offer and sets the terms.
Keep the steps distinct. Sending an online request is not the same as receiving an offer, and an offer is not a loan until you choose to accept it and complete the lender’s required steps. An application doesn’t guarantee a lender match, approval, specific terms, or same-day funding.
What happens after you submit an online request?
Details you submit may be used to connect you with potential lenders in the network. If a lender reviews your information and presents an offer, that lender makes its own eligibility decision and provides its own loan terms. Read the lender’s disclosures and agreement carefully. Check the amount, costs, repayment schedule, and total repayment before deciding whether to accept.
The process is a sequence, not a promise of funding:
- Submit: Provide information through the online request.
- Connect: Your details may be used to identify potential lender options.
- Review: A lender evaluates the request and determines whether to make an offer.
- Decide: Review the lender’s terms and choose whether to accept. Submitting a request does not mean you have agreed to a loan.
How can you move forward without rushing the decision?
Start with the amount you need and consider whether the proposed payment fits your income and upcoming essential expenses. Compare the offer with other options available to you. If the terms don’t fit your budget or you don’t understand a disclosure, pause. A fast application doesn’t remove the need to understand the obligation.
Use a verified application destination and share personal information only when you understand where it’s going. Review the lender’s identity and written terms before signing or authorizing a transaction. If you’re looking for an instant cash loan today, move through the review promptly, but decide only after you understand the offer. QuickCashDirect’s online funding request lets you explore potential options, with no guarantee of a match, approval, specific terms, or funding time.
Make Your Next Funding Decision With Confidence
A text message can point you toward an application, but it can’t tell you whether a loan is right for you. Verify the source, identify the lender, and read the offer’s costs, repayment dates, and total amount due before accepting. If the payment won’t fit alongside essential expenses, pause and consider your options.
QuickCashDirect is an online referral service, not a direct lender. It connects applicants with a network of lenders across the United States. Submitting a request doesn’t guarantee a lender match, approval, specific terms, or funding by a particular time. The lender makes its own decision and presents its own offer.
If you’re looking for an instant cash loan today, take a careful next step: review potential online funding options, then decide only after you understand the lender’s terms. You can move forward with urgency and still protect your budget.
Frequently Asked Questions
Can you really get a loan by text message?
A text message can point you to a loan application, but it can’t approve a loan or guarantee funds. It may be a promotion, an application link, or an update. The lender reviews your application and provides any offer and terms. Before sharing information, verify the sender and destination independently. If you receive an offer, read the lender’s disclosures and agreement before deciding whether to accept.
Are text message loan offers legitimate?
Some messages may come from legitimate businesses, while others may be misleading or fraudulent. Branding and urgent language alone don’t prove who sent a text. Find the lender’s contact details independently, check its identity, and inspect the destination before entering personal information. Be cautious if the message hides loan terms or pressures you to act before you can review the offer. Pause if you can’t verify the source.
Can I get an instant cash loan today through a text?
A text can’t guarantee an instant loan or same-day funds. Timing depends on separate steps, including application review, the lender’s decision, completing the agreement, processing cutoffs, and the receiving bank’s availability. If a message promises immediate funds without explaining conditions, treat the claim cautiously. Before relying on money for an urgent bill, review the actual lender’s terms and deposit timing. An application or approval doesn’t mean funds have arrived.
Do text message loans require a credit check?
Credit-review requirements vary by lender and loan product. A text that claims “no credit check” doesn’t establish how the lender will assess your application or guarantee approval. Depending on its criteria, a lender may consider information beyond a traditional credit score. Read the lender’s disclosures and privacy terms to understand what information it may collect and how it may use that information when reviewing your application.
What should I check before clicking a loan text link?
Verify the sender and lender independently before using a link. Check that the destination matches the lender’s legitimate website, and don’t enter banking credentials through an unexpected message. Review the privacy information and loan disclosures, including payment dates, fees, and total repayment. If the message feels unusually urgent or key details remain unclear, pause. Find the business’s contact information separately rather than relying on the text.
How does a loan referral service differ from a lender?
A loan referral service can collect application details and connect applicants with potential lenders, but it doesn’t make the lender’s decision. The lender determines eligibility and provides any offer, including its terms and repayment obligations. QuickCashDirect is a referral service, not a direct lender. If you receive an offer, identify the lender and review its disclosures and agreement before deciding whether to accept.
What if I cannot afford the repayment on a fast loan?
Pause before accepting if the payment schedule won’t reasonably fit your budget. Compare each due date with your income and essential expenses, and read the agreement for possible late-payment consequences. If you already have a loan and expect difficulty paying, contact the lender directly to discuss your situation. Consider whether delaying the expense or another available option may be more manageable. Don’t rely on a new loan to repay an existing one without weighing the risks.