
What if the loan that arrives soonest leaves you with the hardest bill to pay? When an urgent expense can’t wait until payday, hardship loans for bad credit may seem like a practical answer. But a low credit score can limit your options, and a quick offer isn’t automatically an affordable one.
The goal is to cover the emergency without creating a second one at repayment time. This guide explains what lenders may mean by a “hardship loan,” which borrowing options you can compare, and how to check total repayment, APR, fees, and due dates before you apply or accept an offer.
You’ll also learn what to look for in lender disclosures, including eligibility, credit inquiries, and funding timing. QuickCashDirect is a referral platform, not a direct lender. It connects applicants with a network that may include short-term loans, cash advances, and installment options. The lender makes the approval decision and sets any offer’s terms, so review the details carefully before moving forward.
Key Takeaways
- Hardship loans for bad credit are a broad label, not one standardized product. Check each lender’s eligibility rules and repayment terms.
- Compare payday loans, installment loans, and cash advances by payment schedule and potential costs, not by advertised speed.
- Use a checklist before applying: test your budget, consider alternatives, verify the lender, read disclosures, and map out repayment.
- QuickCashDirect connects applicants with a lender network. Any available offer and its terms come from the lender, so review the details before accepting.
What Are Hardship Loans for Bad Credit, and When Might They Help?
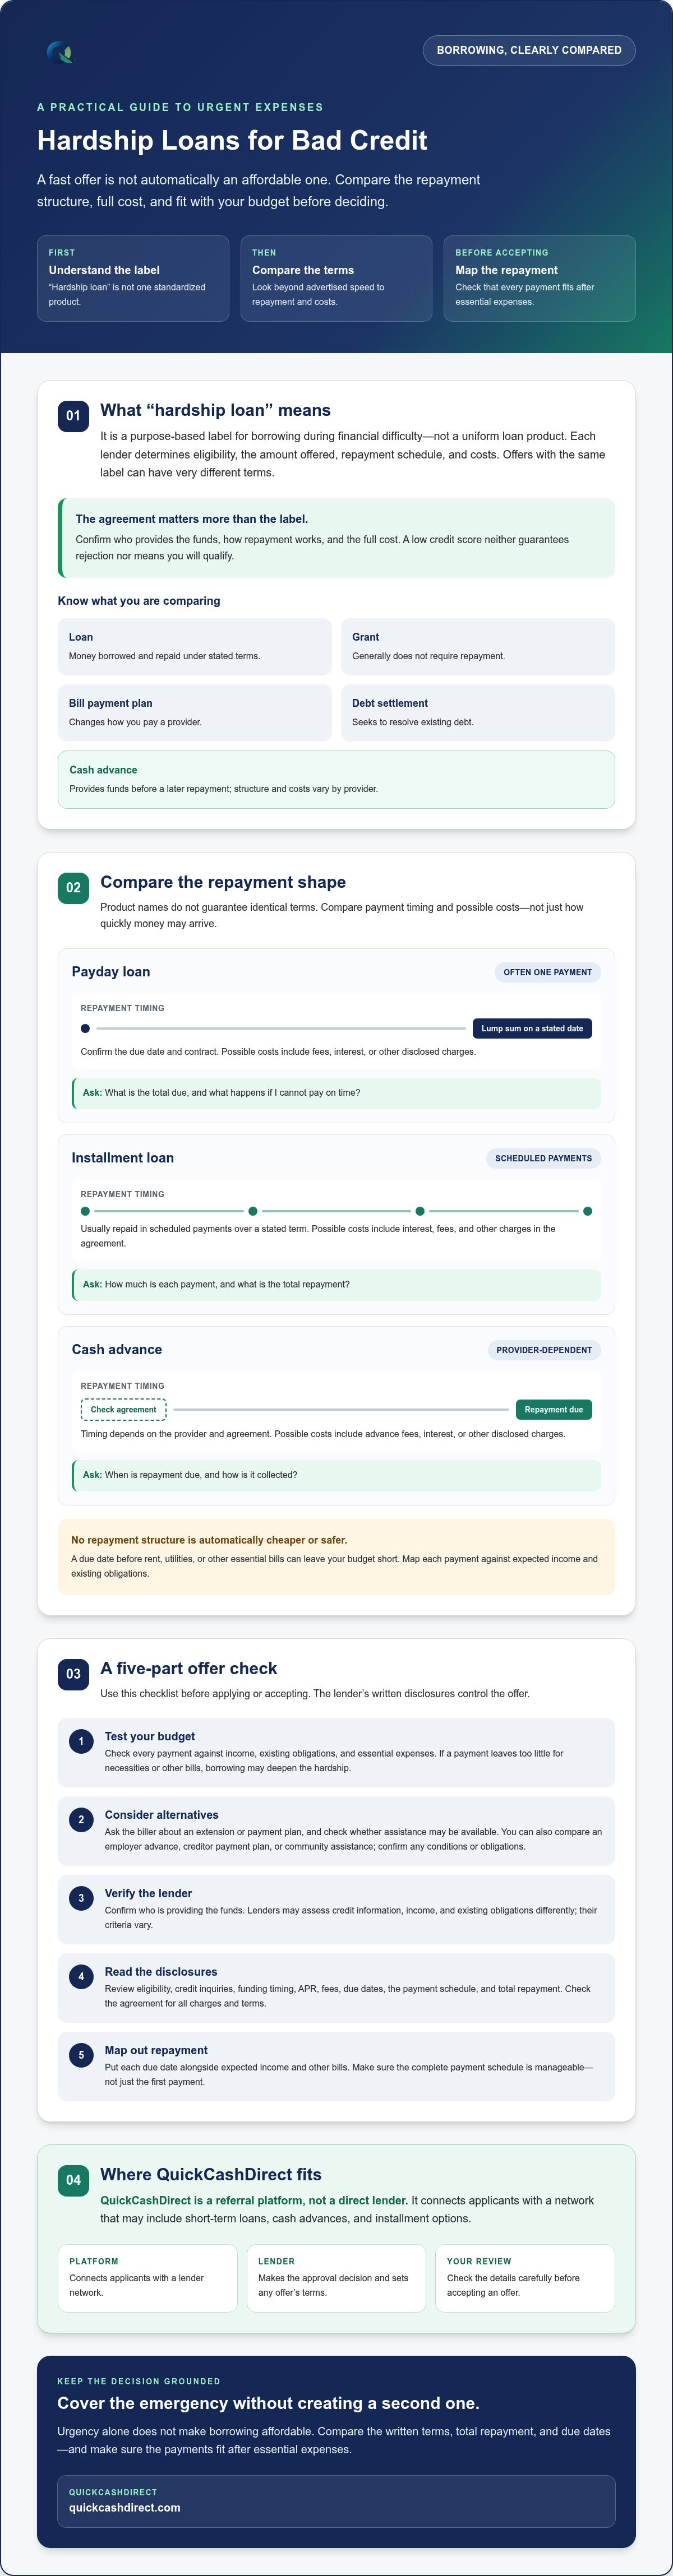
“Hardship loan” is a purpose-based label, not a uniform loan product. It usually describes borrowing to cover an urgent expense during financial difficulty. The lender determines eligibility, the amount offered, the repayment schedule, and the costs. Two offers described as hardship loans can have very different terms, so read the lender’s disclosures rather than relying on the label.
A loan is money you borrow and agree to repay under stated terms. It isn’t the same as a grant, which generally doesn’t require repayment; a bill payment plan, which changes how you pay a provider; or debt settlement, which seeks to resolve existing debt. A cash advance provides funds before a later repayment, but its structure and costs vary by provider. Check the agreement to understand exactly what you’re being offered.
What financial emergencies might lead someone to consider borrowing?
An urgent car repair may affect your ability to get to work. A medical bill or essential household expense may also have a deadline. These situations can prompt someone to consider hardship loans for bad credit, but urgency alone doesn’t make a loan affordable. Before taking on debt, ask the biller about an extension or payment plan, and check whether assistance may be available.
How does bad credit affect hardship loan options?
Lenders may weigh credit information, income, and existing obligations differently. Their criteria vary, and a low credit score neither guarantees rejection nor means you’ll qualify. If you receive an offer, check whether every payment fits your budget after essential expenses. A potential lender may use different criteria to assess borrowers with weakened credit histories, a practice discussed under Subprime lending.
Hardship loans are a purpose-based label for borrowing during financial difficulty, not a standardized product with uniform eligibility or terms. Treat each offer as its own agreement. Confirm who is providing the funds, how repayment works, and the full cost before you decide. If a payment would leave too little for necessities or other bills, borrowing may deepen the hardship rather than solve it.
Which Hardship Loan Options Can Borrowers with Bad Credit Compare?
Compare repayment structure first, not a claim about how quickly money may arrive. Payday loans, installment loans, and cash advances can work differently, and product names don’t guarantee identical terms across lenders. The Consumer Financial Protection Bureau explains the basic structure of a personal loan in its guide to hardship loan options. For broader context, see this bad credit loan guide.
| Option | Repayment timing | Possible cost components | Questions to ask |
|---|---|---|---|
| Payday loan | Often due as a lump sum on a stated date. Confirm the contract. | Fees, interest, or other disclosed charges | What’s the total due, and what happens if I can’t pay on time? |
| Installment loan | Usually repaid in scheduled payments over a stated term. | Interest, fees, and any other charges in the agreement | How much is each payment, and what’s the total repayment? |
| Cash advance | Depends on the provider and agreement. | Advance fees, interest, or other disclosed charges | When is repayment due, and how is it collected? |
How do payday loans and installment loans differ?
A payday loan may require one lump-sum payment, while an installment loan may spread repayment across scheduled payments. The signed terms control. Neither structure is automatically cheaper or safer. If a due date falls before rent, utilities, or other essential bills, repayment can leave your budget short. Map each payment against expected income and existing obligations before deciding.
When might a cash advance or other alternative be worth comparing?
A cash advance may have its own fees, repayment rules, and eligibility conditions. Compare those details with an employer advance, a creditor’s payment plan, or community assistance. These alternatives also have conditions, so confirm what’s available and whether repayment or other obligations apply. Read this cash advance guide for more context, but don’t assume this option fits every emergency.
When comparing hardship loans for bad credit, review the written offer line by line. QuickCashDirect is a referral platform, not the lender. If you want to explore potential options, you can review possible loan options, then check each lender’s disclosures and repayment terms before accepting an offer.
Can a Hardship Loan with Bad Credit Be Affordable? Compare the Full Repayment
Don’t judge an offer by the amount you can borrow or the size of the first payment. Compare the amount you’ll actually receive with the total you must repay, every fee, and each payment date. A loan may cover an urgent bill but still strain your budget if repayment competes with rent, utilities, food, or other essentials.
Affordability depends on both the total obligation and whether each payment fits your budget when it’s due. This matters with hardship loans for bad credit because offers, fees, and schedules can vary by lender. For another perspective on hardship loan options, compare current lender disclosures rather than relying on a product label or general description.
What should you check beyond the amount borrowed?
APR, or annual percentage rate, expresses borrowing costs as a yearly rate to help compare credit offers. The finance charge is the dollar amount the agreement says you’ll pay for borrowing, separate from the amount you receive. Review both, along with the full repayment amount. Check the lender’s disclosures for fees, each payment date, late charges, and renewal or extension terms.
Confirm how payments will be collected. If you authorize automatic withdrawals, line up the dates with your income and essential bills. A withdrawal scheduled before rent or a utility bill could leave too little for necessities. Verify every number in your own offer before accepting. Don’t fill gaps with estimates or assume a term that isn’t stated.
Use a hypothetical budget check
This example uses variables, not lender terms or quoted costs. Replace them with figures from your offer and budget:
- Net amount received: N
- Total repayment, including disclosed charges: R
- Money left after income covers essential expenses and existing obligations: B
- Each scheduled payment: compare it with B on that specific due date
If a payment exceeds what remains in your budget on its due date, the offer doesn’t fit without changing another expense or payment plan. If your budget varies, check each due date separately, not just the overall monthly total.
What risks should borrowers weigh before accepting?
A missed payment or repeated borrowing can add pressure and make it harder to keep up with other obligations. The consequences depend on the agreement and applicable law. Credit reporting and collection practices can also vary. Read the lender’s terms to confirm what may happen after a missed payment, how the lender handles collection, and whom to contact to dispute an error. If those details aren’t clear, ask before signing.
How to Evaluate a Hardship Loan Offer Before You Apply
Pause before sharing personal details or accepting an offer. Use this checklist to screen hardship loans for bad credit and compare practical fit, not just the advertised amount.
- Check your budget. Identify the expense, the amount you need, and what you can repay after essential bills.
- Compare alternatives. Ask the creditor or service provider about an extension or payment arrangement. Depending on your situation, check whether employer assistance, nonprofit credit counseling, or community support is available. Don’t assume every option will be offered or suit your needs.
- Verify who’s involved. Confirm the lender’s legal identity and contact details. Check applicable licensing requirements through relevant official sources. If you’re using a referral platform, distinguish it from the lender that would make the credit decision.
- Read the disclosures. Review the APR, fees, repayment dates, late-payment terms, and any renewal or extension language. Read privacy notices and consent language before submitting personal information. Make sure you understand who may receive it and how it may be used.
- Plan repayment. Match each payment date to expected income and essential expenses. If the schedule leaves a shortfall, don’t proceed until you understand your options.
What documents and details might an application request?
An application may ask for identity, contact, income, or bank-account information. Requirements vary by lender, so verify what’s requested and why before providing it. An application is not approval, and submitting one doesn’t confirm the terms you’ll receive. Don’t send sensitive details through an unverified email, text, or website. Check the site address and the recipient’s identity first.
For more context on one type of short-term borrowing, read this online payday loan guide. Use it as a product explainer, not a substitute for reviewing the specific lender’s offer and disclosures.
Compare the options before you commit
Contact the biller directly to ask whether an extension or payment plan could address the immediate deadline without a new loan. You can also check for employer assistance, nonprofit credit counseling, or community support in your area. Availability and eligibility vary. Compare any option’s timing, requirements, and obligations with the loan offer. Choose only what addresses the bill and fits your repayment capacity.
QuickCashDirect is a referral platform, not a direct lender. If you want to explore potential options through its lender network, check potential loan options. Review the current privacy and consent information before submitting details, and read any lender-specific offer carefully before accepting.
How QuickCashDirect Connects Borrowers with Potential Hardship Loan Options
QuickCashDirect is a loan referral platform, not a direct lender. It connects applicants with a network of lenders that may include providers of short-term loans, cash advances, and installment options. The platform doesn’t make the final credit decision or set a lender’s terms. Each lender determines whether an applicant qualifies, what terms may be offered, and whether funding is available.
An inquiry can help you explore potential hardship loans for bad credit, but it doesn’t guarantee a match, approval, or funding. The steps and choices presented can depend on the current platform process. Read the on-screen information carefully, especially before submitting personal details or agreeing to share them.
What happens after submitting an inquiry?
The current application process should explain what information is requested and what consent you’re providing. Don’t assume what happens next based on an advertisement or another application. Review the stated process and privacy disclosures before continuing.
If a prospective lender presents an offer, the lender provides the offer details, disclosures, and loan agreement. Check the lender’s identity and contact information. Then review the amount, APR, fees, repayment dates, and other terms in the actual documents. Confirm who you’re authorizing to receive your information and what you’re agreeing to before proceeding. An inquiry alone isn’t a loan agreement.
How can borrowers make a careful next move?
Start with a defined expense and request only the amount needed to address it. Then check that the proposed payments fit your budget on each due date. Compare any available offers side by side, including total repayment and the consequences of missed payments. A possible option isn’t automatically a suitable one.
If an offer doesn’t fit your budget or goals, decline it. You don’t need to accept simply because a lender responds or presents terms. Take time to review the agreement and ask the lender to clarify anything you don’t understand. QuickCashDirect can help you explore potential lender options, but it can’t promise that you’ll receive an offer, qualify, or get funded.
Ready to explore potential loan options? Review potential loan options, then compare any lender’s disclosures and repayment terms before accepting.
Make Your Next Step With the Repayment in Mind
Hardship loans for bad credit can help address an urgent expense, but the label doesn’t tell you whether an offer fits your budget. Compare total repayment, fees, and payment dates. Check that each payment leaves room for essential bills, and consider extensions or other alternatives before taking on new debt.
Payday loans, installment loans, and cash advances have different repayment structures. Review the actual agreement, verify the lender’s identity, and understand the disclosures before accepting. An application or referral doesn’t guarantee approval, specific terms, or funding.
QuickCashDirect connects applicants with a network of lenders. Potential options may include payday loans, cash advances, and installment loans, while each lender makes its own decisions and sets its own terms. If you’re ready to explore possibilities, explore potential loan options and compare any offer carefully before moving forward.
Take time to choose a path that addresses the immediate need without putting your next set of essential bills at risk. A clear repayment plan can help you move ahead with greater confidence.
Frequently Asked Questions
Can I get a hardship loan with bad credit?
You may be able to find hardship loans for bad credit, but approval depends on the lender’s criteria. Lenders may consider credit information, income, and existing obligations differently, so a low score doesn’t determine the outcome by itself. It also doesn’t guarantee an offer or mean borrowing is affordable. Before accepting, check the lender’s requirements, total repayment, fees, and payment dates against your budget.
What is the easiest hardship loan to get with bad credit?
There isn’t one type that’s easiest for everyone to qualify for. Payday loans, installment loans, and cash advances can have different eligibility rules and repayment structures, and each provider makes its own decision. Don’t choose based only on an “easy approval” claim. Check who the lender is, what information it uses, the complete cost, and whether the required payments fit your budget.
Can I get a hardship loan without a credit check?
Some lenders may assess applications differently, but don’t assume an offer involves no credit check. The lender or application disclosures should explain whether it may review credit information and whether an inquiry could affect your credit file. Before submitting personal details, review the consent language and ask the prospective lender what checks it performs. A referral platform can’t guarantee a lender’s review process or decision.
How much can I borrow with bad credit for an emergency?
The amount, if any, depends on the lender’s eligibility rules and its review of your application. There’s no single amount that applies to every borrower with bad credit. Start with the specific expense and identify the smallest amount that would address it. Then compare the amount you’d receive with total repayment and each due date. Don’t treat an advertised maximum as an amount you can necessarily qualify for or afford.
Will applying for a hardship loan hurt my credit?
It depends on the lender’s process and the type of credit inquiry, if any. Before applying, ask whether the lender may make a hard inquiry or report account activity to credit bureaus. Review the application’s consent and privacy disclosures so you know what you’re authorizing. If you use a referral platform, check its current disclosures too, and confirm any credit-check details directly with the prospective lender.
What should I do if I cannot repay a hardship loan on time?
Contact the lender as soon as you think you may miss a payment. Ask what options, fees, or other consequences may apply, and review your agreement for late-payment and collection terms. Get any revised arrangement in writing and keep records of your communication. Don’t assume an extension or renewal is available. Avoid taking out another loan before comparing its full cost and considering whether it could add to your financial pressure.
Is QuickCashDirect a direct lender?
No. QuickCashDirect is a referral platform that connects applicants with a network of lenders. Potential options may include payday loans, cash advances, and installment loans. The prospective lender makes the credit decision, sets the terms, and determines whether funding is available. An inquiry through the platform doesn’t guarantee a match, approval, or funding. Review the platform’s current consent details and each lender’s disclosures before proceeding.