
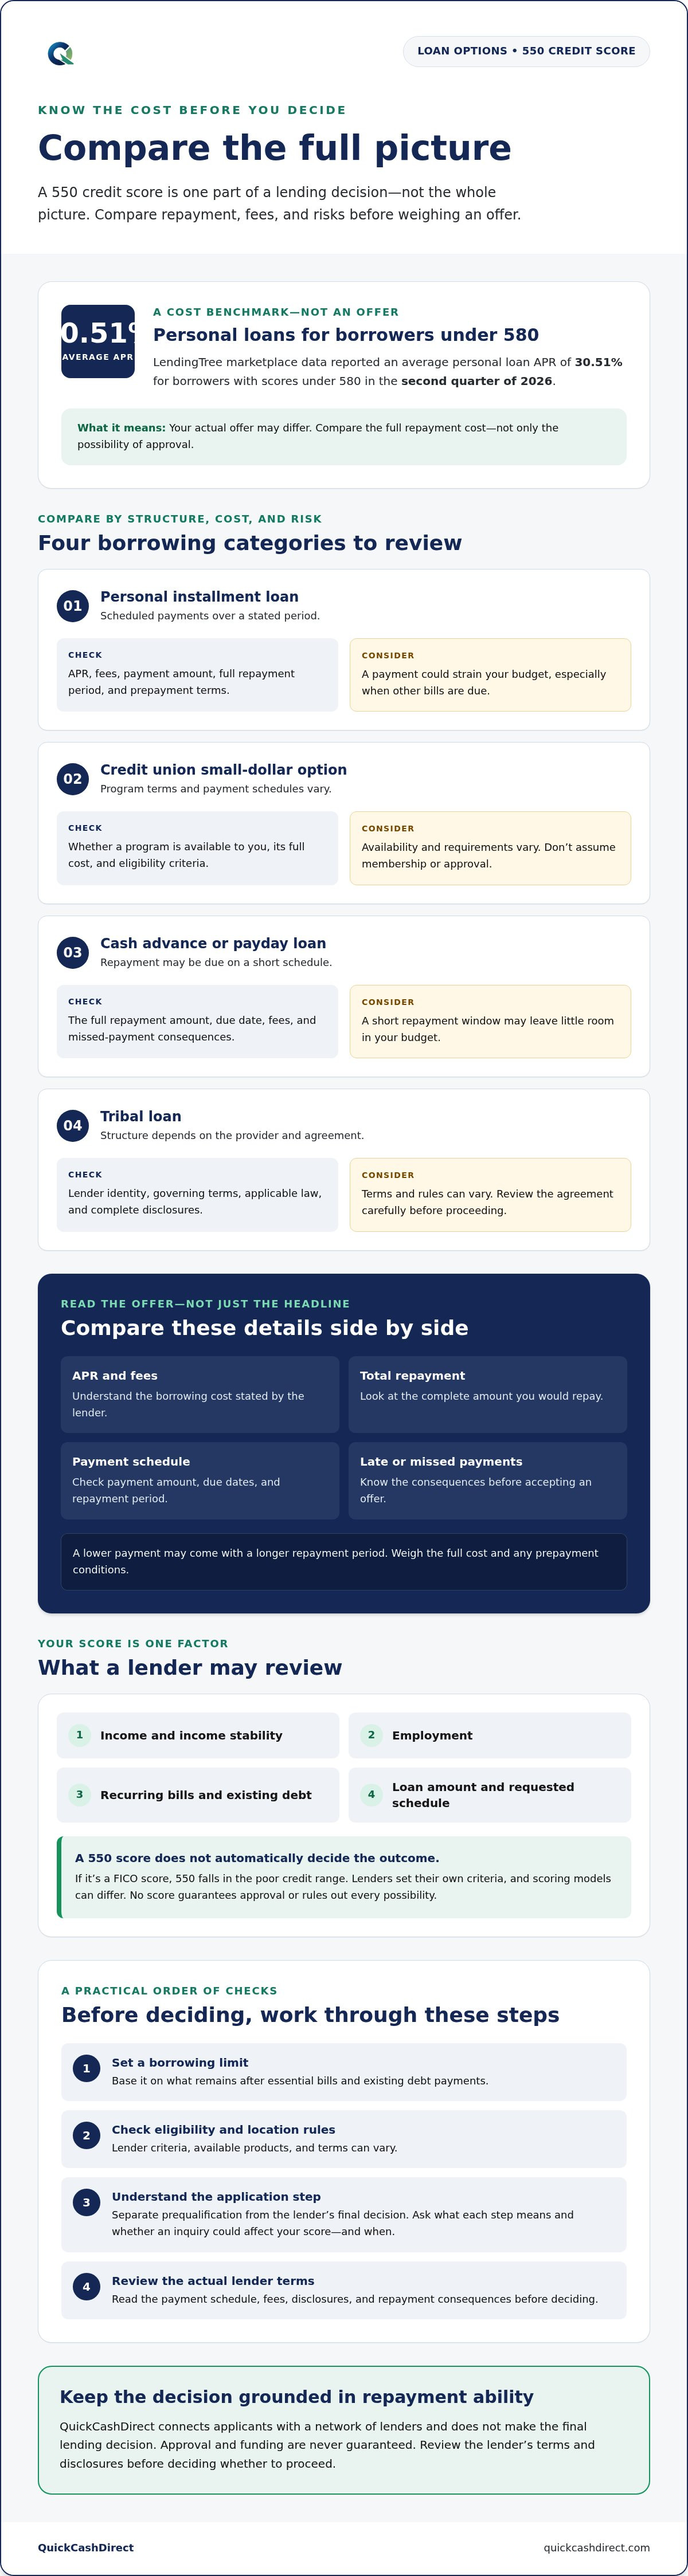
A 550 credit score is one part of a lending decision, not the whole picture. Loan options for 550 credit score borrowers can vary, and a low score may mean fewer choices, higher costs, or a denial. LendingTree marketplace data put the average personal loan APR for borrowers with scores under 580 at 30.51% in the second quarter of 2026. That figure is a reminder to compare the full repayment cost, not just the chance of approval.
If you’re worried about rejection or need money quickly, it can be tempting to accept the first offer. Take time to check the payment schedule, fees, and what happens if you can’t repay on time. Your score matters, but lenders may also consider income, employment, existing debts, and other details.
This guide compares borrowing categories, explains what lenders may review, and shows how to weigh costs and risks before applying. You’ll learn about bad-credit personal loans, secured loans, credit union alternatives, and short-term options. Use the details in each lender’s offer to identify a next step that fits your budget and repayment ability. Approval and funding are never guaranteed.
Key Takeaways
- Compare loan options for 550 credit score borrowers by repayment structure, fees, and the questions to ask before proceeding.
- Check whether a credit union small-dollar option or personal installment loan better matches your needs and repayment capacity.
- Separate prequalification from a lender’s final decision, and confirm what each step means before applying.
- Set a borrowing limit based on what remains after essential bills and existing debt payments.
- QuickCashDirect connects applicants with a network of lenders. Review the lender’s terms and disclosures before deciding whether to proceed.
What a 550 Credit Score Means When Comparing Loan Options
A 550 score can make borrowing more challenging, but it doesn’t determine the outcome by itself. If it’s a FICO score, it falls in the poor credit range. Lenders may assess your full application, and their criteria can differ. A decision may also depend on the amount and type of loan you request, your finances, and the rules that apply where you live.
A credit score is one signal in your application, not a complete assessment of your ability to repay. Scoring models can use different methods, so your score may differ across models or credit-reporting sources. Read this Credit score overview for background on scoring models. When comparing loan options for a 550 credit score, check each lender’s criteria and disclosures instead of assuming one score tells the whole story.
Does a 550 credit score automatically disqualify you?
No single score guarantees approval or rules out every possibility. Lenders set their own criteria, and some may weigh factors beyond your credit score. Your application may be considered, but that doesn’t confirm that you qualify or will receive particular terms. Before applying, check the stated eligibility details, including any location restrictions, and make sure the product fits your needs.
What else may lenders review besides your score?
A lender may consider income, employment or income stability, recurring bills, existing debt, and the repayment schedule you request. What a lender reviews and how it assesses the information can vary. Don’t assume every lender uses the same credit check. Read the application disclosures or ask whether the lender may use an inquiry that could affect your score, and at what stage.
Eligibility, available products, and loan terms depend on the lender’s review and applicable state rules. Compare the actual offer and repayment schedule before deciding. QuickCashDirect is a referral platform that connects applicants with a network of lenders; it doesn’t make the final lending decision. Review the lender’s disclosures and terms before proceeding.
Compare Loan Options for a 550 Credit Score by Cost and Repayment
Compare the full cost and payment schedule, not just how quickly you might receive funds. Loan options for 550 credit score borrowers can differ in structure, lender, and availability. A credit score is one factor in a lender’s review, not a complete measure of repayment ability, as the Consumer Financial Protection Bureau explains. Use each lender’s disclosures to compare APR, fees, total repayment, due dates, and the consequences of late or missed payments.
| Option | Repayment structure | What to check | Risk to consider |
|---|---|---|---|
| Personal installment loan | Scheduled payments over a stated period | APR, fees, payment amount, full repayment period, and prepayment terms | A payment may strain your budget, especially if other bills are due at the same time. |
| Credit union small-dollar option | Terms and payment schedule depend on the program | Whether a program is available to you, plus its full cost and eligibility criteria | Availability and requirements vary. Don’t assume membership or approval. |
| Cash advance or payday loan | Repayment may be due on a short schedule; check the specific offer | Full repayment amount, due date, fees, and missed-payment consequences | A short repayment window may leave little room in your budget. |
| Tribal loan | Structure depends on the provider and agreement | Lender identity, governing terms, applicable law, and complete disclosures | Terms and rules can vary. Review the agreement carefully before proceeding. |
Installment loans and credit union alternatives
Scheduled payments can make it easier to plan, but only if the payment fits your budget. Check how long repayment lasts and the total amount you’ll repay. If you’re considering a credit union, find out whether it offers a small-dollar program you can access, then compare its disclosures with other offers. A lower payment may come with a longer repayment period, so weigh the full cost and any prepayment conditions.
Cash advances, payday loans, and tribal loans
These products can differ in provider, repayment structure, and requirements. Check who would make the loan and read the full terms before sharing information or accepting an offer. For more background, see the cash advance guide. You can also review this comprehensive bad credit loan guide to compare broader borrowing considerations.
QuickCashDirect is a referral platform, not a direct lender. It connects applicants with a network of lenders. If you explore its available loan categories, review the specific lender’s terms and disclosures before deciding whether to proceed.
Will a 550 Score Get You Approved? Check the Risks Before Applying
No. A 550 score alone can’t guarantee approval, determine every offer, or show whether a loan will fit your finances. Lenders set their own criteria and may review other application details. The Federal Trade Commission explains how lenders use credit scores, but each lender’s decision process and terms can differ.
Read prequalification language carefully. It may indicate that you could meet initial criteria, but it isn’t necessarily a final offer or approval. The process varies, so check whether the lender will verify your information, run a credit inquiry, or change proposed terms before making a decision. A preliminary result doesn’t confirm that funds or a specific rate will be available.
A loan is affordable only when its scheduled payments fit your budget. Include essential expenses, existing debt payments, and the timing of your income in that calculation. A payment that looks manageable on its own may still leave too little for rent, utilities, food, or other bills.
How to assess the full cost of an offer
Review the APR, finance charges, origination fees, late fees, and total repayment amount in the lender’s disclosures. Match each due date and payment frequency to your expected income and essential expenses. Don’t judge affordability by advertised speed or one payment figure alone. Check what you’ll repay over the full schedule and what happens if a payment is late or missed.
What to check before accepting short-term credit
Before accepting a short-term offer, read the agreement for renewal or rollover terms, default consequences, collection practices, and late-payment conditions. Confirm the lender’s identity and contact details, and check whether the offer is available where you live. Terms and applicable rules can vary by provider and location, so don’t rely on a headline or summary alone.
Pause if you can’t understand the terms, confirm who the lender is, or make the scheduled payment without borrowing again. These are reasons to reassess the offer and compare other loan options for 550 credit score borrowers. QuickCashDirect connects applicants with a network of lenders and doesn’t make the final lending decision. You can review available loan categories, then read the specific lender’s disclosures before deciding whether to proceed.
How to Compare and Apply for a Loan with a 550 Credit Score
Use a clear sequence: set your limit, compare providers, read the disclosures, and then decide whether to apply or accept an offer. This helps you focus on loan options for 550 credit score borrowers that fit your budget instead of choosing based on speed or a preliminary result.
Prepare your information and set a repayment limit
Start with your regular income, essential expenses, current debt payments, and the amount you actually need to borrow. Subtract bills and debt obligations from expected income to see what remains. Set a payment limit that leaves room for routine costs and unexpected needs. If a proposed payment uses up that cushion, reconsider the amount or the offer.
Application questions and verification requirements vary by lender. Provide only the information requested through the lender’s disclosed application process. Before sharing personal or financial details, make sure you understand who is collecting them and how the information may be used.
Review lender terms before you submit or accept
Compare providers using complete disclosures, not just a headline rate or payment estimate. Check the lender’s identity, eligibility conditions, costs, payment dates, and contact information. Read privacy and credit-inquiry disclosures before submitting an application. Credit-check practices and criteria differ, so a “no credit check” label doesn’t explain everything about a lender’s review. For related questions, read this no-credit-check loan guide.
A displayed match or preliminary result isn’t necessarily final approval or a confirmed offer. Review the final lender’s agreement and make sure the payment schedule still works for your budget before accepting.
Use this four-step checklist before moving forward:
- Set a borrowing limit based on what you need and can repay.
- Compare providers and check the lender’s identity and eligibility criteria.
- Review complete costs, payment dates, privacy terms, and credit-inquiry disclosures.
- Decide only after reviewing the final terms and confirming the payments fit.
QuickCashDirect is a referral platform that connects applicants with a network of lenders, not a direct lender. Its available loan categories can help you explore possible options, but the specific lender’s terms and disclosures determine what you’re being offered.
Choose a 550 Credit Score Loan Option That Fits Your Situation
The right choice depends on what you need, how soon you need it, and what your budget can support. Compare loan options for 550 credit score borrowers by the amount required, repayment schedule, and total cost. A quick offer isn’t automatically the right offer. Before taking short-term credit, consider whether another approach, such as asking a bill provider about payment arrangements, could give you more time without adding a loan payment.
Which option may fit your borrowing need?
If you can plan for regular payments, compare installment structures and the full repayment amount disclosed by each lender. Check the payment amount and dates against your budget after essential bills and existing debt obligations. For an urgent need, first consider whether short-term repayment would leave enough for your next set of expenses. Don’t accept a schedule that seems manageable only if you borrow again or skip another bill.
For broader comparison guidance, see this easy loans for bad credit guide. Use it to inform your questions, then rely on the specific lender’s current disclosures to evaluate an offer.
What to expect from a loan referral platform
QuickCashDirect connects applicants with a network of lenders. It isn’t the lender; participating lenders make their own decisions about applications, eligibility, and terms. A connection or displayed option isn’t a promise of approval or funding. Check each lender’s identity, requirements, repayment details, and disclosures independently before moving forward.
Take the next step only after reviewing the terms and confirming you can manage the scheduled payments. You can review available loan options through QuickCashDirect, then assess any lender’s offer on its own terms. Availability, eligibility, and decisions vary by lender and may depend on your location and application details.
Make Your Next Borrowing Decision With Confidence
A 550 score is one part of a lender’s review, not a promise of approval or a complete picture of your finances. Before choosing among loan options for 550 credit score borrowers, compare the full repayment cost, fees, payment dates, and missed-payment terms. Then confirm that the scheduled payment fits your budget after essential expenses and current debt obligations.
QuickCashDirect connects applicants with a network of lenders. Its listed categories include payday loans, cash advances, and tribal loans, but the platform isn’t the lender. Participating lenders make their own decisions, and terms and availability can vary. Review each lender’s eligibility requirements and disclosures before deciding whether to proceed.
Before moving forward, compare the terms carefully and make sure repayment looks manageable. A clear comparison can help you choose a path that supports your needs without putting your budget under added pressure.
Frequently Asked Questions
Can I get a loan with a 550 credit score?
Possibly, but a 550 score doesn’t guarantee approval or rule it out. Lenders set their own criteria and may consider income, existing debts, and other application details alongside your score. Offers and eligibility can vary by lender and location. Check the requirements before applying, then review the full repayment amount and schedule to confirm the loan fits your budget.
What loan options are available for a 550 credit score?
Potential options may include personal installment loans, secured loans, credit union small-dollar programs, cash advances, payday loans, or tribal loans, depending on the provider and your circumstances. Loan options for 550 credit score borrowers differ in cost, repayment schedule, and availability. QuickCashDirect is a referral platform that connects applicants with lenders and lists payday loans, cash advances, and tribal loans among its categories. Review each lender’s terms independently.
What is the easiest loan to get with a 550 credit score?
There’s no loan type that’s easiest for every borrower. A lender’s criteria, your income and obligations, location, and requested repayment schedule can all affect its decision. Short-term credit may have different costs and repayment risks than a loan with scheduled installments. Compare total repayment, due dates, and fees before applying. Don’t choose an offer simply because its application appears quick or simple.
Will applying for a loan with a 550 credit score hurt my credit?
It depends on the lender’s credit-check process. Some providers may use a soft inquiry for an initial review, while a formal application may involve a hard inquiry that can affect your credit score. Practices vary, so read the lender’s disclosures before submitting your details. If you’re unsure, ask which type of inquiry may be used and when it could occur.
Can I get a personal loan with a 550 credit score?
It may be possible, but approval and terms depend on the lender’s review. Some lenders consider factors beyond a credit score, such as income and existing debt, while others may have score requirements that affect eligibility. Compare the APR, fees, payment amount, and total repayment disclosed in each offer. Consider a secured option only after understanding what collateral is at risk if you can’t repay.
How much can I borrow with a 550 credit score?
There’s no fixed amount tied to a 550 score. The amount, if any, depends on the lender’s criteria, your application, requested loan purpose, income, debts, and applicable availability. Don’t borrow the maximum amount shown just because it’s offered. Work out what you actually need and what payment you can manage after essential expenses and existing debt obligations, then compare the lender’s full repayment terms.
Are no-credit-check loans guaranteed with a 550 credit score?
No. “No credit check” doesn’t mean guaranteed approval, eligibility, or funding. Providers may use other information to review an application, and their criteria differ. Check what inquiries may occur, who the lender is, and what the agreement says about repayment, fees, and late payments. Treat preliminary results as unconfirmed until you’ve reviewed the lender’s final offer and disclosures.
Ready to explore possible next steps? Review available loan options, compare the specific lender’s terms, and proceed only if the scheduled payments fit your budget.