
What if your bankruptcy discharge wasn't a permanent barrier to emergency funding, but a clean slate for a faster recovery? You've completed the complex legal process of a filing. However, life doesn't stop for car repairs or medical bills. Finding payday loans after bankruptcy can feel like an impossible task when traditional banks reject your applications immediately. You're likely feeling the pressure of mounting bills and the confusion of a shifting credit landscape in 2026. It's a stressful position. You don't have to face it without a sense of safe, structured relief.
We understand that you need immediate solutions, not more delays. This guide provides the exact steps to secure immediate cash today while beginning the vital process of rebuilding your financial life. You'll learn how to identify lenders who prioritize your current income over your past credit history. We'll also break down the latest regulatory changes and the most efficient ways to bridge financial gaps without risking your fresh start. Stop the cycle of rejection. Start moving toward a state of resolution right now.
Key Takeaways
- Confirm immediate eligibility for emergency cash following a Chapter 7 discharge without waiting years for credit repair.
- Learn how to secure payday loans after bankruptcy by prioritizing current recurring income over past credit history.
- Navigate Chapter 13 restrictions by identifying when you need trustee permission before incurring new debt.
- Use a professional referral network to bypass traditional bank rejections and connect with specialized lenders instantly.
- Gather your income verification and discharge papers to ensure a high-velocity application and direct deposit in minutes.
Can You Get Payday Loans After Bankruptcy in 2026?
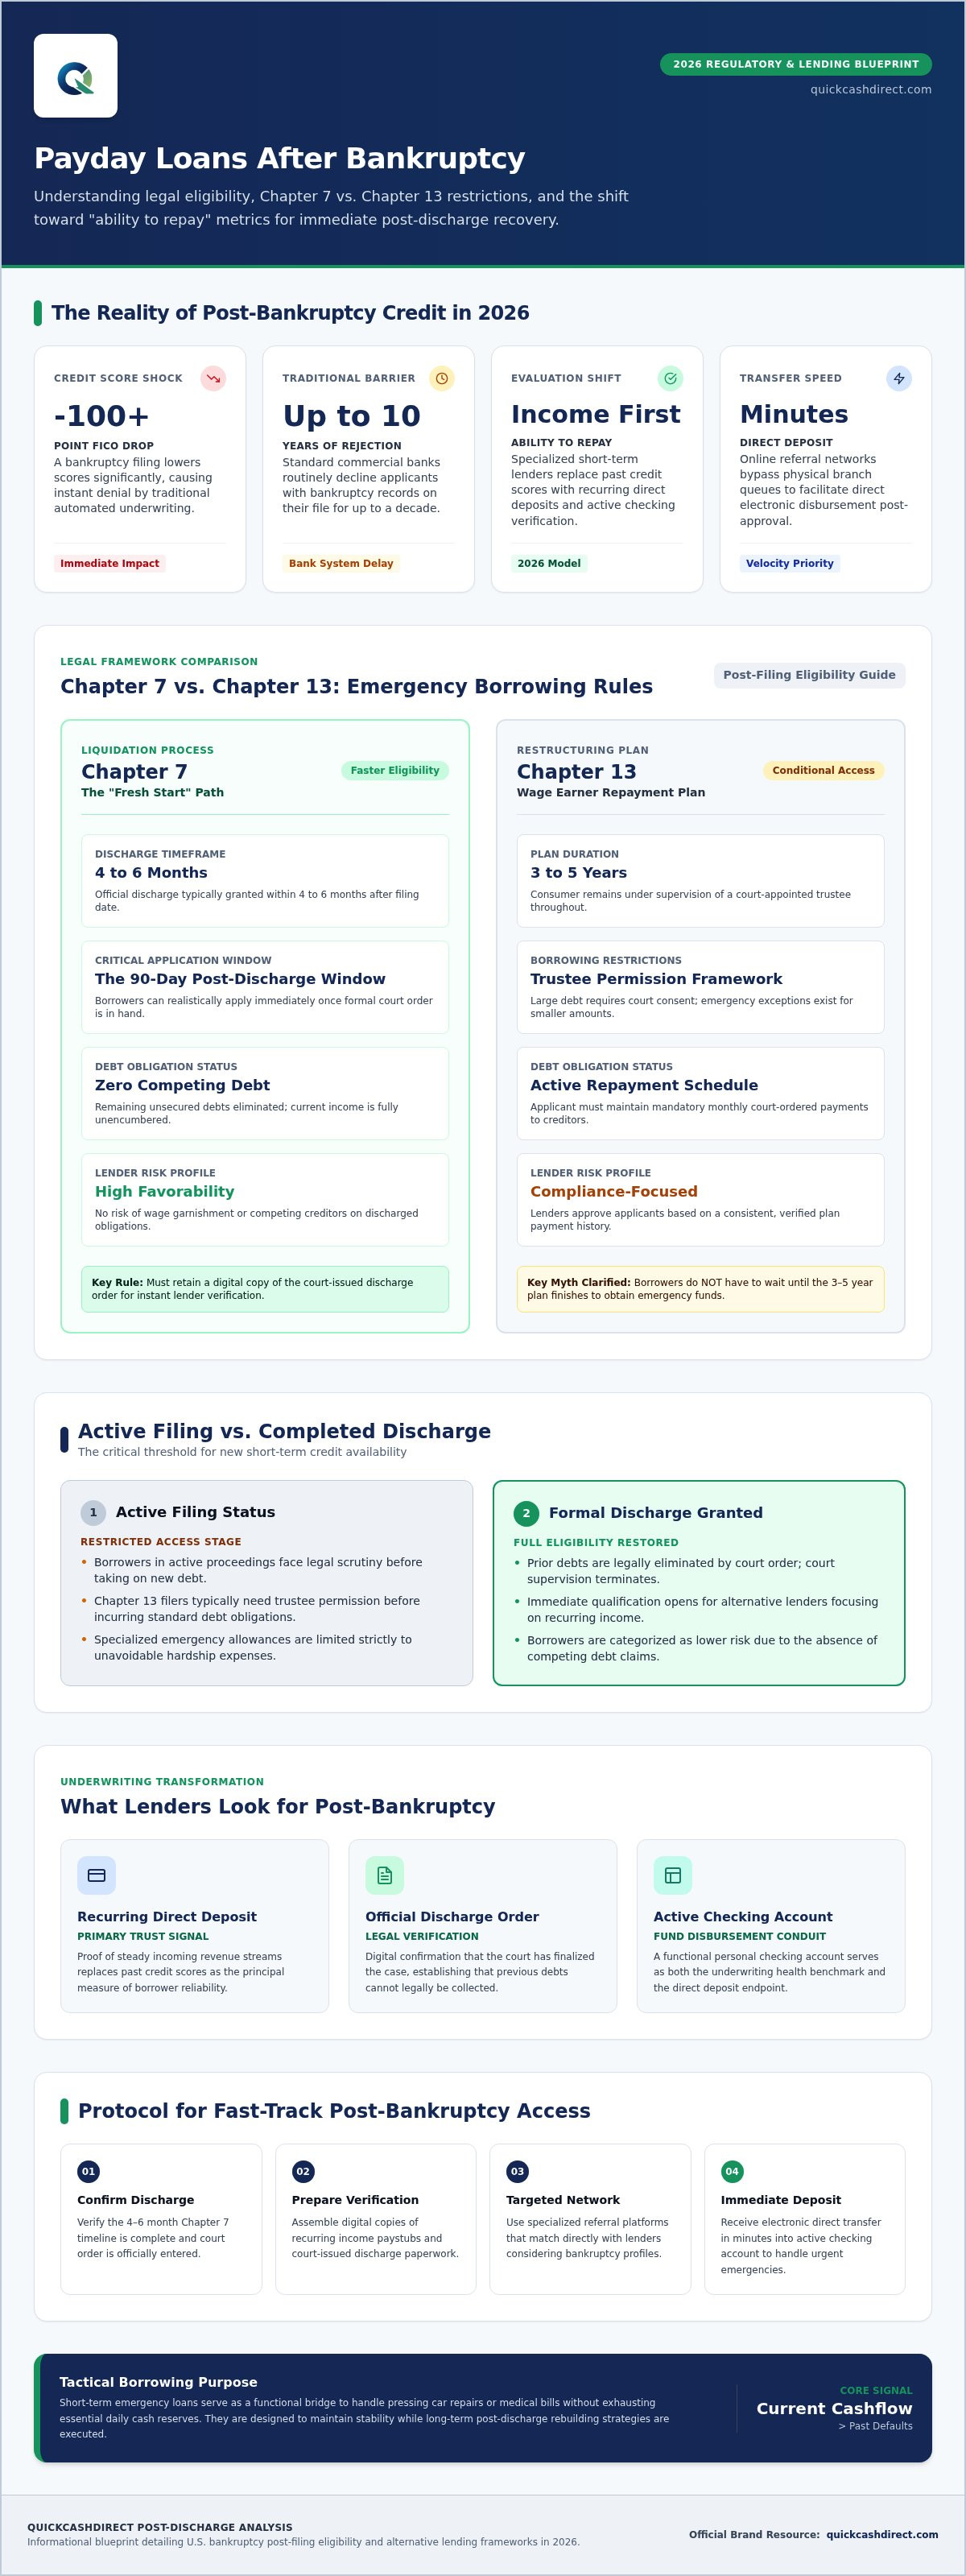
Securing a payday loan after bankruptcy is a viable option for many consumers in 2026. While traditional banks often reject applicants with a bankruptcy history for up to a decade, alternative lenders focus on your current financial stability. The key factor is your status within the legal framework of bankruptcy in the United States. If you have received a formal discharge, you are generally eligible to apply for new credit immediately. This discharge signals that your previous debts are legally cleared; this makes you a lower risk for certain short-term lenders who prioritize your present ability to repay over past defaults.
There is a critical distinction between an active filing and a completed discharge. Borrowers in an active Chapter 13 plan face legal restrictions and usually require court permission to incur new debt. However, once you have your discharge papers for a Chapter 7 or Chapter 13 case, the path to emergency funding opens. Online referral services specialize in this transition. They connect you with lenders who understand that a past bankruptcy does not define your current financial reliability.
The Reality of Post-Bankruptcy Lending
A bankruptcy filing lowers your FICO score significantly. In many cases, scores drop by 100 points or more. Payday lenders operate on a different model that bypasses these traditional barriers. They prioritize a steady income and an active checking account as primary trust signals. In 2026, the industry has shifted toward "ability to repay" metrics. Lenders look for recurring direct deposits rather than a perfect credit report. This specific approach allows you to access payday loans after bankruptcy even when your score is still in the early stages of recovery. It's a functional bridge to financial resolution.
Why Emergency Loans Matter During Recovery
Unexpected expenses don't wait for your credit to rebuild. A car repair or medical bill can trigger a financial downward spiral if left unaddressed. Tactical borrowing provides a structured way to handle these emergencies without depleting your essential cash reserves. Unlike long-term debt, these short-term loans are designed to bridge a specific gap. Use them as a tool to maintain your daily life while you execute your long-term rebuilding strategy. Speed is the priority here. Online referral networks facilitate this by matching your profile with lenders who can provide direct deposit in minutes. This efficiency removes the stress of traditional bank delays and provides immediate relief when you need it most.
Understanding Eligibility: Chapter 7 vs. Chapter 13
Your eligibility for payday loans after bankruptcy depends heavily on which chapter you filed. Each legal path has different rules for incurring new debt. Understanding these distinctions is the first step toward securing emergency cash. Lenders evaluate your risk based on whether your previous debts are legally eliminated or if you are still making court-ordered payments. Clear documentation is your best tool for a fast approval.
Borrowing During Chapter 7 Recovery
Chapter 7 is known as the "Fresh Start" bankruptcy. It liquidates non-exempt assets to pay creditors and discharges remaining unsecured debts. High-risk lenders often view Chapter 7 filers favorably once the case is closed. You have no competing debt obligations. This makes your current income more available for new loan repayments. Most borrowers receive an official discharge in bankruptcy approximately four to six months after their initial filing date.
The 90-day window following your discharge is a critical time. You can realistically apply for funding as soon as you have the court order in hand. Lenders will require proof that your case is finalized. Keep a digital copy of your discharge papers ready for instant upload. This document proves you are no longer legally responsible for old debts. It serves as a powerful trust signal for lenders who focus on your current financial capacity.
Managing Chapter 13 Restrictions
Chapter 13 involves a three to five year repayment plan. You are technically under the supervision of a court-appointed trustee during this time. A common myth suggests you cannot borrow any money until the plan ends. This is incorrect. While you generally need trustee permission for large loans, emergency exceptions exist for smaller amounts. Lenders specializing in payday loans after bankruptcy often accept Chapter 13 filers who demonstrate a consistent payment history toward their plan.
Speed is essential in an emergency. If you face an urgent bill, you can structure your application by highlighting your steady income and plan compliance. Some lenders operate within specific frameworks that allow for quick advances without lengthy court delays. You can connect with lenders who understand Chapter 13 requirements through our streamlined referral process. This efficiency allows you to bridge the gap while remaining in good standing with the court.
- Chapter 7 Timeline: Apply immediately after your discharge order is signed.
- Chapter 13 Timeline: Apply anytime with trustee approval or after your final plan payment.
- Required Docs: Discharge Order, two most recent pay stubs, and 30 days of bank transaction history.
Payday Loans vs. Traditional Rebuilding Tools
Choosing the right tool depends on your timeline. Secured credit cards help build credit, but they require a cash deposit and take weeks to arrive. If you need immediate cash, payday loans after bankruptcy provide the speed that traditional tools lack. You don't have to wait for a physical card in the mail. Instead, you get direct deposit in minutes to handle urgent bills today. Accessibility is the primary driver for post-discharge borrowers who can't yet qualify for standard bank products.
The Fast Funding Advantage
The biggest advantage is velocity. Traditional rebuilding tools often involve a two-week processing period and a mandatory security deposit. Most payday referrals don't require upfront cash to open an account. This makes them ideal for immediate resolution of utility shut-offs or car repairs. You resolve the crisis first. Then you focus on long-term recovery. This tactical approach prevents a single emergency from becoming a secondary financial disaster.
Speed comes with specific trade-offs. It's essential to understand the bankruptcy in the United States framework and the definition and costs of payday loans before signing a contract. These loans are designed for short-term utility rather than long-term financing. While the costs are higher than standard bank loans, the utility of having cash in your account within minutes often outweighs the price during a genuine emergency. Use these loans as a bridge, not a permanent solution.
Rebuilding Credit Long-Term
Recovery is a multi-step process. Using no credit check loans allows you to manage the current gap while your credit report updates. Once you stabilize your immediate situation, you can transition to loans for bad credit that offer longer repayment terms. On-time payments are the foundation of your new financial life. Every successful transaction builds a history of reliability.
Consistent performance on short-term obligations prepares you for stable installment options. You're moving from a state of need to a state of resolution. By using payday loans after bankruptcy as a temporary fix, you protect your cash flow. This protection gives you the breathing room needed to apply for secured cards or credit-builder loans later. Focus on speed now to ensure your long-term success.
How to Apply for Loans Post-Bankruptcy: A Step-by-Step Guide
Applying for payday loans after bankruptcy requires a structured approach to ensure speed and safety. You don't have time to waste on traditional banks that demand a perfect credit history. Follow this sequence to transition from a state of need to a state of resolution. Efficiency is your primary tool in this process. By following a logical path, you minimize friction and move toward a fast financial result.
- Gather your documents: Prepare a digital folder with your two most recent pay stubs and your bankruptcy discharge papers. Having these ready prevents delays during the verification phase.
- Use a referral service: Don't apply to individual lenders one by one. This is inefficient. Use an online referral platform to scan multiple bankruptcy-friendly lenders simultaneously.
- Verify direct deposit: Provide accurate routing and account numbers. This ensures your funds arrive without technical errors.
- Review the agreement: Look for clear repayment dates and total costs. Transparency is a recurring safety marker in reliable lending.
- Accept and fund: Once you sign the electronic agreement, the lender initiates the transfer. This high-velocity process puts cash in your account quickly.
Maximizing Approval Chances
Lenders in 2026 prioritize your current income stability over past legal filings. Your ability to repay is a more significant trust signal than a traditional credit score. When you seek direct deposit loans in minutes no credit, you bypass the standard barriers that cause rejection. Accurate income reporting is essential. Use a single referral platform to protect your profile. This prevents multiple hard inquiries that could hinder your long-term credit rebuilding efforts. Focus on your recurring income as your primary qualification tool.
Avoiding Post-Bankruptcy Pitfalls
Safety and security are the foundations of a successful recovery. Always verify lender legitimacy through secure, established referral networks. Avoid unlicensed storefronts that lack transparent terms. Set a realistic repayment schedule before you accept any funds. Use the "Urgency, Efficiency, Resolution" framework for every financial decision. Address the urgent bill immediately. Use an efficient loan tool to bridge the gap. Reach a resolution that preserves your fresh start. This structured approach prevents new debt cycles and keeps your recovery on track. You can submit your request through our secure network to find a lender that fits your specific post-bankruptcy needs today.
Speed is the objective. By gathering your proof of income and discharge status beforehand, you ensure the fastest possible processing time. Most lenders in our network specialize in bad credit scenarios. They understand that a bankruptcy discharge represents a clean slate. Use this to your advantage. Provide clear, honest data to secure the funding you need to move forward.
Fast Funding with QuickCashDirect: Your Path to Resolution
QuickCashDirect serves as the essential bridge between your financial crisis and a fast solution. We understand that a bankruptcy discharge isn't an end point. It's a new beginning. Finding payday loans after bankruptcy shouldn't be a secondary struggle. Our platform simplifies the search by connecting you with a network of lenders who look beyond your credit report. They prioritize your current income and your ability to move forward. This efficiency transforms a complex problem into a manageable sequence of steps. You get the support you need without the traditional bank delays.
The Referral Advantage
Access a diverse network of lenders with one simple online form. You don't have to navigate multiple websites or face repeated rejections from traditional institutions. Our network includes specialized options like tribal loans and cash advances. These lenders are experienced in high-risk scenarios and post-bankruptcy filings. Emergencies do not wait for business hours. Our referral system operates 24/7 to ensure you have access to help whenever a crisis occurs. This constant availability provides a sense of calm, structured relief when you need it most. Submit your request and see your options instantly.
Security is the foundation of our professional service. We use industry-standard protocols to protect your sensitive information throughout the referral process. This safety allows you to focus on your recovery without worrying about your privacy. Our platform is the preferred choice for easy loans for bad credit because we streamline the connection between you and the right lender. You move from application to an offer in minutes. Once you accept, the lender initiates the direct deposit process. This is the velocity required for a true financial resolution.
Ready for Your Fresh Start?
Transition from the stress of unexpected bills to the relief of a funded account. You've already done the hard work of completing your bankruptcy. Now, use the tools available to protect your progress. A short-term loan provides the bridge you need to keep your life moving. Don't let a temporary gap derail your long-term credit rebuilding plan. Secure your emergency cash today and maintain your momentum toward financial stability. QuickCashDirect accelerates the path to recovery by matching bankruptcy survivors with lenders capable of delivering direct deposits in minutes.
Take the final step toward resolving your emergency. Review your offers, sign your agreement, and watch for your funds. The path from a state of need to a state of resolution is shorter than you think. Start your request now to secure the cash you need to protect your future.
Take Control of Your Financial Recovery Today
You now have the essential framework to navigate your post-discharge financial landscape. Bankruptcy is a strategic legal reset that clears the path for a faster recovery. You don't have to wait years for traditional credit scores to rebound before addressing a modern emergency. By prioritizing your current income and discharge status, you can successfully secure payday loans after bankruptcy to bridge immediate financial gaps. This structured approach protects your hard-earned progress and prevents unexpected bills from derailing your fresh start.
Transition from a state of high stress to a state of calm resolution right now. Our streamlined platform connects you with a diverse network of lenders for all credit types. We utilize a secure 256-bit encrypted application to ensure your sensitive data remains protected throughout the process. Experience the velocity of direct deposit in minutes to resolve your crisis today. Apply Now for Fast Post-Bankruptcy Funding and claim the relief you deserve. Your financial recovery is a sequence of manageable steps. Take this logical action to maintain your forward momentum and secure a more stable future.
Frequently Asked Questions
Can I get a payday loan if my bankruptcy is not yet discharged?
It is difficult to secure new debt while a bankruptcy case is active. For Chapter 7 filers, most lenders wait for the official discharge to ensure previous debts are legally cleared. Chapter 13 filers must typically obtain written permission from their court-appointed trustee before incurring new obligations. Taking out a loan without this authorization can jeopardize your legal standing. Focus on reaching your discharge date before seeking payday loans after bankruptcy for the best results.
Do payday lenders check for past bankruptcies?
Most lenders perform a specialized inquiry that identifies past legal filings. However, they prioritize your current ability to repay over your historical credit mistakes. They look for a steady source of income and an active checking account rather than a perfect FICO score. This approach allows them to offer payday loans after bankruptcy to individuals who have a discharge on their record. Your current recurring direct deposit serves as the primary trust signal for approval in these scenarios.
How much can I borrow immediately after a bankruptcy discharge?
Initial loan amounts are determined by your current recurring income rather than your bankruptcy history. Most first-time borrowers in a post-discharge scenario qualify for small loans ranging from $100 to $1,000. Lenders evaluate your debt-to-income ratio to ensure the repayment is manageable. As you establish a successful history of on-time payments with a lender, you may become eligible for higher limits. Always borrow only what you need to resolve your immediate emergency situation.
Will a payday loan help or hurt my credit rebuilding efforts?
Standard payday loans rarely impact your FICO score because most short-term lenders don't report to the three major credit bureaus. They primarily use subprime databases for verification. While this means on-time payments won't necessarily boost your score, it also means the inquiry won't further damage your rebuilding efforts. However, failing to repay can lead to collections, which will appear on your report. Use these loans as a bridge to more stable installment options.
What is the fastest way to get cash after filing for bankruptcy?
Using an online referral platform is the most efficient method to secure emergency cash. These services scan a wide network of lenders simultaneously to find those who specialize in bad credit and post-bankruptcy scenarios. This high-velocity process bypasses the delays of traditional bank applications. You can often receive a direct deposit in minutes once you sign your electronic agreement. This speed is essential for resolving urgent bills like car repairs or utility shut-off notices.
Are tribal loans a better option than payday loans after bankruptcy?
Tribal loans provide a specialized alternative for borrowers who face rejection from traditional storefronts. These lenders operate under the sovereign jurisdiction of federally recognized tribes rather than state-specific laws. This often allows them to offer flexible eligibility criteria for individuals with a recent bankruptcy discharge. While they serve as a functional bridge for emergency needs, you must review the specific terms and repayment dates carefully. They are a reliable tool for transitioning from a state of need to resolution.
What documents do I need to apply for a post-bankruptcy loan?
You must provide verifiable proof of your current financial status and legal discharge. Prepare your two most recent pay stubs and a bank statement showing at least 30 days of transaction history. You will also need your official bankruptcy discharge papers to prove the case is closed. Having these digital files ready for instant upload ensures a high-velocity application process. Lenders use this data to confirm your recurring income and your eligibility for fast funding options.
Can I apply for a loan if I have a Chapter 13 repayment plan in progress?
You can apply for funding during an active Chapter 13 plan, but you must follow specific legal steps. Most court-ordered repayment plans require you to obtain permission from your bankruptcy trustee before taking on new debt. Incurring unauthorized debt can lead to the dismissal of your case. Some lenders specialize in these scenarios and can provide the necessary documentation for your trustee. Always consult your attorney to ensure compliance with your specific court-ordered repayment schedule.